Quick Answer:
-
What it is: a freehold waterfront community by Sobha Realty in MBR City.
-
Ready vs new: the original is largely built; Hartland 2 is off-plan.
-
For Indians: you buy freehold and remit funds under the RBI's LRS.
-
Yield: 2026 portal data shows gross yields near 6%, with rents easing.
-
Tax: Dubai rent and gains stay taxable in India.
Sobha Hartland is a freehold waterfront community in Mohammed Bin Rashid City, the kind of ready, family-focused address that suits an Indian buyer who wants rent from day one. This guide is the honest version, not a brochure.
Here is the part the listings skip. The market is not only climbing. Market trackers reported both asking and actual rents in the community easing through 2026 (reported by property portals, not an official Dubai Land Department figure). A home here can still be a sound buy, but you should go in with real numbers.
So this guide covers the location, how the ready community differs from off-plan Hartland 2, what homes really cost and yield, and exactly how an Indian buyer sends money and handles the tax. For nearby options, see our guide to townhouse communities. We checked every rule against Sobha Realty, the RBI, the Income Tax Department and DLD pages on 20 October 2026.
Inside the Hartland Community
The Sobha Hartland location is its strongest card. The community sits in Mohammed Bin Rashid (MBR) City, opposite Downtown Dubai and beside the Ras Al Khor Wildlife Sanctuary, so it feels green and calm while staying close to the centre.
The Community
The community is run by Sobha Realty across about 8 million square feet with a large green belt and a waterfront along the canal. It is freehold, so foreign buyers, Indians included, can own a home here outright and pass it on. Two international schools sit inside it, Hartland International School and North London Collegiate School Dubai, which is why families settle here and rent stays steady. Our rental yield guide shows how school-led communities hold their tenants.
Ready Not Off-Plan
Most of the original Hartland is built and lived in. A dated Sobha statement reported in the press put it around half complete with roughly 1,100 homes built and 2025 handover targets, so by late 2026 the earlier phases are handed over and some later towers are finishing. Delivered clusters include Waves, Creek Vistas, Greens and The Crest.
For an Indian buyer this matters in two ways. A ready home earns rent now, and a ready home with a title deed can support a UAE residence visa, which an off-plan unit cannot until it is handed over. Here is the community at a glance, from Sobha Realty's own description.
|
Feature |
Detail |
|---|---|
|
Developer |
Sobha Realty |
|
Area |
MBR City, Nad Al Sheba |
|
Size |
About 8 million sq ft |
|
Tenure |
Freehold |
|
Homes |
Apartments, townhouses and villas |
|
Schools |
Two international schools on site |
In short, this is a built, lived-in community, not a construction site. For an Indian buyer, that brings three practical advantages:
-
Rent from day one: a ready home earns income immediately, not after a build.
-
Visa support: a registered title deed can back a UAE residence visa.
-
See before you buy: you inspect the actual home and tower, not a show flat.
That alone sets it apart from most new launches an Indian buyer gets shown.
Location and Daily Access
Location drives the rent and the resale, so it is worth being precise about what is confirmed and what is not.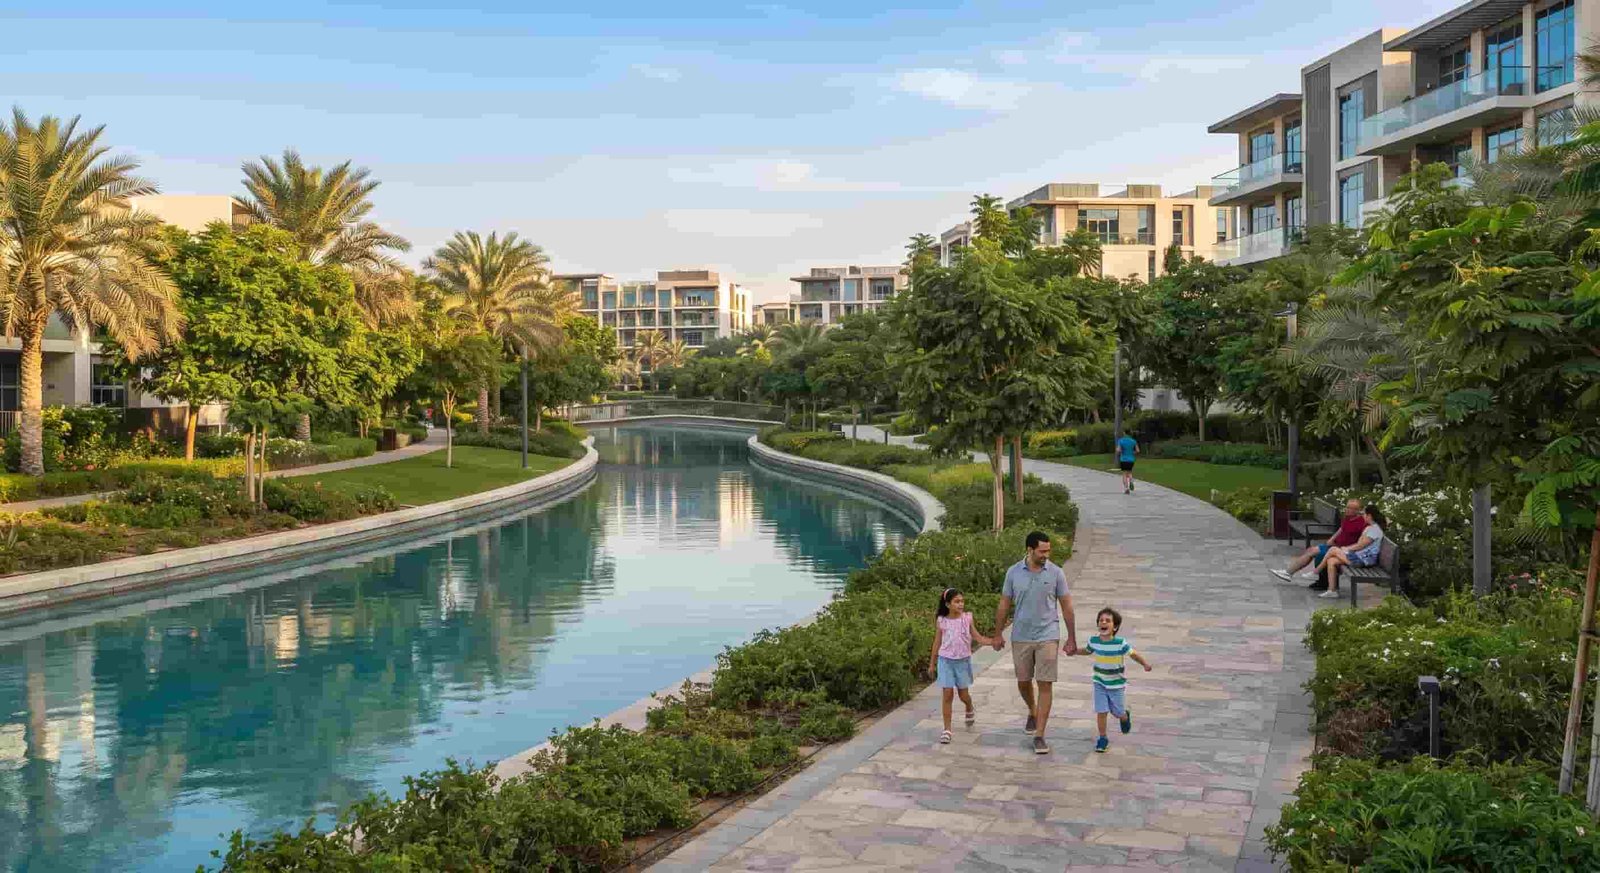
Where It Sits
Hartland sits inside MBR City, which Sobha describes as opposite Downtown Dubai, with the Ras Al Khor sanctuary on one side and the canal running through it. Sobha's own figure for the original community is about 24 minutes to the city centre. You will see "7 to 10 minutes to Burj Khalifa" online, but that line comes from a press report about Hartland 2, so treat it as a rough guide. Exact distances to DIFC, the airport and the nearest Metro appear only on broker pages, so check them on a map before you rely on them.
Family Appeal
The two schools, the green belt and the waterfront make this an end-user area, not just an investor play. That is what keeps tenants in place and voids low, which is the part of a yield that brochures never mention. Before you commit, our guide to Dubai property valuation explains how to price a home against real sales.
A built community is only half the choice, though. The name you are shown might be the newer one.
Hartland or Hartland 2
The Sobha Hartland vs Hartland 2 question trips up a lot of buyers, because they are two separate developments with similar names, each about 8 million square feet, side by side in MBR City. Knowing which one you are being sold is the first thing to settle.
The Key Difference
The original Hartland is largely delivered, so you buy a ready home and rent it out now. Sobha Hartland 2 launched in November 2022, is mostly off-plan, and is built around a crystal lagoon with a beach edge. Its first completion target of 2025 has slipped, so handovers there are phased and still running. Which one fits you depends on whether you want income now or a staged payment plan.
|
Point |
Sobha Hartland |
Sobha Hartland 2 |
|---|---|---|
|
Status |
Largely ready |
Mostly off-plan |
|
Buy for |
Rent from day one |
Capital growth |
|
Signature |
Green belt and canal |
Crystal lagoon |
|
Visa fit |
Taskeen or Golden Visa |
Golden Visa now, Taskeen after handover |
|
Payment |
Mostly on completion |
Developer payment plan |
Choose ready Hartland for income, or Hartland 2 for a staged plan into a newer product. If you are still weighing communities, our network guide to luxury apartments compares the prime Dubai areas.
Which to Pick
The Sobha Hartland payment plan options mostly sit with Hartland 2, because the original is largely sold and now trades on the resale market, where you usually pay in full on transfer. Any payment plan you see is the developer's own term for Hartland 2, not a guarantee from us, so read it against the handover dates before you sign.
|
Thinking about Hartland? Our expo team shows Indian buyers the real DLD transaction prices behind a project, not just the asking prices in listings, and walks through the LRS steps before you book. You leave knowing the true number, not a brochure figure. |
Price and Rental Yield
Here is where honesty matters most, because the public price data is thin. The sobha hartland price picture has to be read carefully, and anyone quoting an exact figure is usually quoting a listing, not a sale.
What Homes Cost
Sobha does not publish "from" prices, and the DLD open-data portal sits behind a security check, so there is no clean official figure to quote. Market trackers in 2026 put apartments in the low millions of dirhams and villas much higher, but those are listing numbers, reported by property portals, not official DLD sales. Treat them as a guide, and check real transaction prices before you offer. As a rough feel, a mid-range apartment near AED 2 million is about ₹5.2 crore, at the RBI reference rate of ₹25.88 per dirham on 15 October 2026 and before fees.
The Real Yield
The Sobha Hartland rental yield is the number buyers chase, so read it with care. Market trackers in 2026 reported gross apartment yields near 6%, with rents easing over the year. Sobha's own site claims "over 6%", but it gives no source or method, so do not bank on it.
Gross is not what you keep. Service charges, agent fees and empty weeks all come off the top, so a real net yield usually lands well below the headline. Here is what to subtract from any yield figure you are shown.
|
What you see |
What to check |
|---|---|
|
Advertised yield |
Is it gross or net? |
|
Rent quoted |
Asking rent or actual DLD rent? |
|
Service charge |
The AED per sq ft a year |
|
Agent and DLD fees |
One-off costs on entry and exit |
|
Vacancy |
Weeks empty between tenants |
A net yield after all of that is the figure that pays you, so judge the home on that, not the brochure's gross.
How Indian Buyers Pay
For an Indian buyer, India's money and tax rules shape the deal more than any amenity. They change with where you live, so settle which group you are in first.
Sending Money Over
Resident Indians fund a Dubai home under the RBI's Liberalised Remittance Scheme. The main rules are simple:
-
The cap: USD 250,000 per person per financial year, PAN required.
-
Your own money: Indian banks cannot lend for it, so the funds must be yours. The remittance goes out under purpose code S0005, the RBI's label for investment abroad in real estate.
-
Pooling: family members in India can combine their yearly limits for one purchase.
On the Dubai side, budget for the DLD transfer fee of 2% from the buyer and 2% from the seller, 4% in total.
Your bank collects Tax Collected at Source of 20% on remittances above ₹10 lakh in a year, under Section 206C(1G). The Budget 2026 cut to TCS applied to education and medical transfers, not to property, so property buyers still pay the 20%. It is not a lost cost, though: you set it against your income tax when you file, or claim it back.
Your bank will usually need Form 15CA, and sometimes Form 15CB from a CA, so line that up early. For the full journey, see how to buy through our Mumbai expo.
When you later sell, the money route depends on your account: NRE balances are fully repatriable, while an NRO account is capped at USD 1 million per financial year, so set up the right account before you buy.
Tax Back Home
Do not believe the "tax-free" line. An ordinarily resident Indian is taxed in India on worldwide income, so your Dubai rent and any sale gain go into your Indian return. Under the India-UAE tax treaty, that income may be taxed in the UAE too, and India gives credit for any UAE tax paid, which is usually nil, since the UAE charges no personal income tax. You must also report the home as a foreign asset in Schedule FA every year.
NRIs living in the UAE are different. While they stay non-resident, India taxes them only on income received or arising in India, so Dubai rent received abroad generally falls outside it. The trap is the deemed-resident rule: an Indian citizen with roughly ₹15 lakh or more of Indian income who pays no tax anywhere else can be treated as resident, so ask a chartered accountant if that might be you.
The Visa Question
A home worth AED 2 million or more can open a UAE Golden Visa, and both a ready Hartland home and an off-plan Hartland 2 unit from an approved developer can qualify. The old rule that you had to pay 50% upfront was dropped in January 2024, and a mortgaged home now just needs a no-objection letter from your bank.
Official UAE sources differ on the visa's length. DLD's service describes a 10-year renewable permit, while the federal u.ae portal lists real-estate investors under a 5-year visa, so confirm the current term with the ICP or GDRFA before you rely on either.
There is also a 2-year investor visa, the Taskeen. It has no minimum value for a sole owner and needs a share of at least AED 400,000 for a joint owner, but it requires a registered title deed. So a ready Hartland home qualifies, while an off-plan Hartland 2 unit cannot until it is handed over. When you plan your exit, our guide to selling in Dubai covers the resale route.
Before you commit to any Hartland home, run through this short checklist:
-
Check the real price: use actual DLD transaction prices, not asking prices.
-
Work out the net yield: subtract service charges, fees and likely void weeks.
-
Confirm the visa route: match the home to the Golden or Taskeen rules.
-
Plan the money: line up your LRS limit, TCS and account before you book.
Put the honest picture together, and the decision gets simpler.
See Hartland for Yourself
Whether Sobha Hartland is a good investment comes down to the numbers, not the brochure: a ready, freehold, family community with sound fundamentals and a yield that is good but softening, so buy on real DLD prices and a net figure. Weigh it against off-plan Hartland 2 on whether you want rent now or a payment plan, and plan the LRS and tax steps before you commit.
Planning a viewing trip? Our note on the Mumbai to Dubai route helps you time it.
Want the real transaction prices and an adviser's answers? Register for the Expo and meet our team in your city.
Frequently Asked Questions
Is Sobha Hartland a good investment in 2026?
It can be. The community offers a ready, freehold home in a strong family area, with gross yields reported near 6%. But rents are easing, so buy on real DLD transaction prices and a net yield, not the brochure figure.
Sobha Hartland me investment kaisa hai?
A ready, freehold community with steady demand and reported gross yields near 6%. Rents are softening in 2026, so check actual DLD prices and your net yield after service charges before you buy.
Is the community freehold for Indians?
Yes. The community is freehold, so Indian citizens and NRIs can own a home outright. You fund it under the RBI's LRS, up to USD 250,000 per person a year, with 20% TCS above ₹10 lakh.
What is the rental yield here?
Market trackers in 2026 reported gross apartment yields near 6%, with rents easing. That is a gross figure. After service charges, agent fees and empty weeks, your real net yield is lower, so judge the home on the net.
How does it differ from Hartland 2?
They are two separate communities in MBR City. The original Hartland is largely built, so you buy ready and rent now. Hartland 2 launched in 2022, is mostly off-plan around a crystal lagoon, and sells on a payment plan.
Do I pay tax in India on a Dubai property?
If you are an ordinarily resident Indian, yes. Dubai rent and sale gains are taxable in India, with credit for any UAE tax paid, usually nil. You must also report the home in Schedule FA each year. NRIs are taxed differently.
Does buying here get me a visa?
A home worth AED 2 million or more can qualify for a Golden Visa. A ready home can also support the 2-year Taskeen visa, which needs a title deed. Confirm the current terms with the ICP or GDRFA.